Certified and SBA-Compliant Business Valuations in Washington DC
A lender-ready valuation is often the document that gets a DC-area deal financed. Bridge delivers one in days, at a flat fee.
When a Washington business is bought, sold, or financed, the conversation usually pauses on one question: what is it really worth, according to someone independent? A certified business valuation from Bridge answers that in a form banks, buyers, and courts accept, grounded in your numbers and the market, for a flat $1,999.
300+
Successful exits
$1B+
in M&A transactions
150+
Years of experience
Schedule Your Free Consultation
Talk to a Bridge advisor and get a clear picture of where your business stands. Learn what it takes to value, grow, or exit with confidence.
Trusted by Small Businesses
What SBA-compliant actually means
For SBA 7(a) loans used to buy a business, the lender has to obtain an independent valuation from a qualified source, and under the SBA rules in effect since October 1, 2026 that now applies to every acquisition, with the old exception for smaller deals removed. The requirement is independence: the number cannot come from either side of the table, and it has to follow accepted valuation methods.
A Bridge certified valuation follows those accepted methods, and Bridge works with more than 50 SBA-approved lenders, so the report lands in the format underwriters already expect to read. Getting your own valuation before the lender orders one also means you go into the deal already knowing the number.
When a deal needs a certified valuation
A free estimate is fine when you just want a range. These are the moments when a lender, a lawyer or a court will ask for the certified version instead.
Financing a purchase
Most SBA-backed acquisitions require an independent valuation before the loan clears.
Buying out a partner
A number neither partner chose keeps the split fair and the working relationship survivable.
Estate and succession planning
A formal value gives your attorney and your accountant something solid to build a transfer around.
Divorce or other legal matters
Courts want an unbiased opinion of value from somebody with credentials behind it.
Raising money
Investors want to see how you reached your number before they will discuss the number.
What your certified report includes
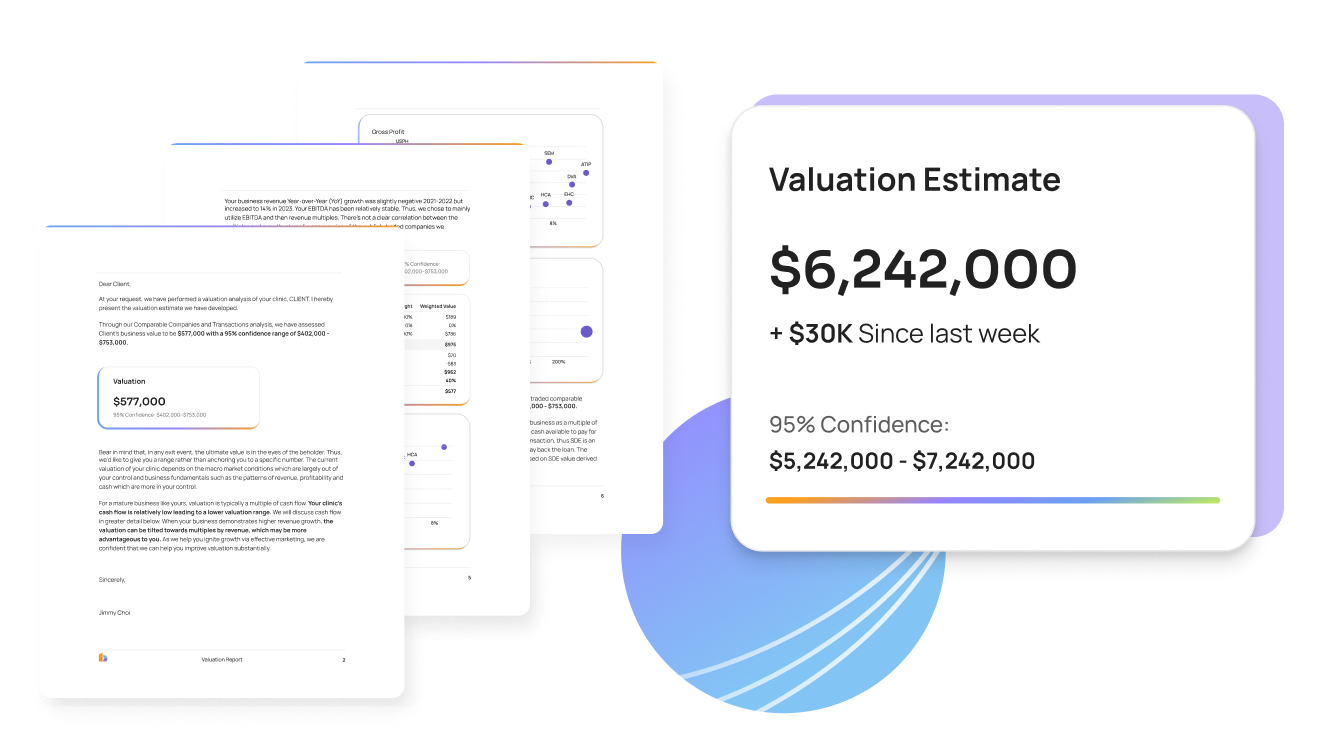
You receive a complete document you can hand straight to a lender or buyer, and your advisor walks you through every part of it: a clear value conclusion with the range and the methods used to reach it; normalized earnings that show what the business truly makes; market multiples and comparables tying your number to real, recent activity; and a read on risk and value drivers, so everyone understands what is behind the figure.
Valuing a DC-area business, and how SBA financing fits
A large share of DC-area companies earn their revenue from federal agencies or from the firms that serve them, and that changes what a careful valuation has to account for. Backlog is not the same as revenue. Funded task orders, option years and a seat on an IDIQ vehicle each carry different weight, and a serious valuation separates work that is contracted and funded from work that is merely available. Set-aside status usually does not transfer. 8(a), SDVOSB, WOSB and HUBZone designations attach to the company’s ownership, so a buyer generally cannot assume them, and revenue that depends on a set-aside is valued accordingly.
Concentration cuts both ways. A long relationship with one agency looks stable until recompete season, and buyers price single-agency and single-vehicle concentration as risk. People are part of the asset. Cleared staff, key personnel named in contracts and incumbent teams are often what a buyer is really acquiring, and their retention terms belong in the analysis. None of this makes a government contractor harder to sell. It means the number has to be built on the details rather than a revenue multiple, which is exactly what a certified report is for.
Every acquisition now requires an independent valuation from a qualified source, requested by and prepared for the lender, and the old exception for businesses valued at $250,000 or less is gone. The lender must also see the debt covered by historical earnings at a coverage ratio of 1.25x, measured on the last fiscal year end or an average of the last two. Knowing the sequence below is how you keep the financing from slowing the sale down.
- Agree on a price. Buyer and seller reach a deal, often using a Bridge valuation as the starting point.
- Lender orders the independent valuation. For larger SBA deals, an unbiased third-party valuation is required before the loan can be approved.
- Underwriting reviews the report. Because Bridge reports arrive in the format underwriters expect, this step goes smoothly.
- Financing is approved and the deal closes. A clean valuation keeps everyone moving toward closing.
The levers that move your number
A valuation is not just a snapshot. It also shows you what is driving your value up and what is holding it back. Across most deals, the same handful of factors decide whether a buyer pays a premium or asks for a discount.
A business that runs without you
An SBA lender is underwriting the business the buyer will run, not the one you run today. The less the operation needs you in it, the less the loan looks like a wager on somebody who is walking out the door.
Cash flow that covers the loan payment
Around a 20% cash-flow margin is the floor most buyers and lenders look for. On an SBA deal the arithmetic is stricter: the earnings have to cover the buyer’s debt service and still pay them a living, or the loan does not clear.
Financials that survive underwriting
Three years of statements that reconcile to the tax returns. An underwriter who has to ask what a line item means is an underwriter adding weeks to a timeline that is already long here.
No single customer carrying the revenue
In a banking and corporate-services town, one large client can quietly become most of your revenue, and that is the risk lenders flag first. Losing a single account should not change whether the loan gets repaid.

Revenue a lender can forecast
Contracted or repeat revenue is worth more per dollar than project work, because a buyer and an underwriter can both model it forward.
Systems written down, team in place
Written processes and a team that makes decisions without you let a buyer picture day one, and let a lender believe the business keeps performing after you hand over the keys.
Owner Stories
THE PROCESS
Getting your valuation in Washington DC
Our straightforward process gets you a defensible number without the guesswork.
Get your valuation report in just 3 days
1. Open your file
Tell Bridge about the business. It takes about 30 minutes.
2. Share your numbers
Upload three years of financial statements through a secure data room.
3. Get the certified report
Lender-ready and SBA-compliant, in 3 to 5 business days.
4. Walk through it
A walkthrough with your advisor is included, so you can explain the number to a lender in your own words.
Serving Washington DC and the DMV
Bridge works with owners across the District, Northern Virginia and suburban Maryland, in the sectors that fill the region: government contracting and professional services, technology and cybersecurity, associations and nonprofits, healthcare practices, construction and specialty trades, staffing, hospitality and restaurants, and home services across Arlington, Alexandria, Fairfax, Loudoun, Montgomery and Prince George’s counties. The team is headquartered in Lehi, Utah, and meets with you by phone and video, so a fast, certified valuation is always within reach.
Order a certified, SBA-compliant valuation, or start with a free estimate to see your range. Questions about your deal? Talk to a Bridge advisor.