SBA and Certified Business Valuation in San Diego
In San Diego, the independent valuation is usually the document a deal waits on. Bridge delivers one in three to five business days, at a flat fee, so the paperwork is not what holds up your closing.
When a San Diego business is bought, sold, or financed, the conversation usually pauses on one question: what is it really worth, according to someone with no stake in the answer? A certified business valuation from Bridge answers that in a form banks, buyers, and courts accept, built from your own financials and what comparable businesses actually closed at, for a flat $1,999.
300+
Successful exits
$1B+
in M&A transactions
150+
Years of experience
Schedule Your Free Consultation
Talk to a Bridge advisor and get a clear picture of where your business stands. Learn what it takes to value, grow, or exit with confidence.
Trusted by Small Businesses
What SBA-compliant actually means
For most SBA 7(a) loans used to buy a business, the lender has to bring in an outside, qualified party to value it once the financed goodwill passes $250,000, or any time the buyer and seller are connected. The requirement is independence. The number cannot come from either side of the table, and it has to be reached by accepted methods rather than a broker rule of thumb.
A Bridge certified valuation meets that standard, which is why Southern California lenders take it without ordering a second appraisal. Bridge works with more than 50 SBA-approved lenders, so the report lands in the format Southern California underwriters already expect to read.
When a deal needs a certified valuation
A free estimate is fine when you just want a range. These are the moments when a lender, a lawyer or a court will ask for the certified version instead.
Financing a purchase
Most SBA-backed acquisitions require an independent valuation before the loan clears.
Buying out a partner
A number neither partner chose keeps the split fair and the working relationship survivable.
Estate and succession planning
A formal value gives your attorney and your accountant something solid to build a transfer around.
Divorce or other legal matters
Courts want an unbiased opinion of value from somebody with credentials behind it.
Raising money
Investors want to see how you reached your number before they will discuss the number.
What your certified report includes
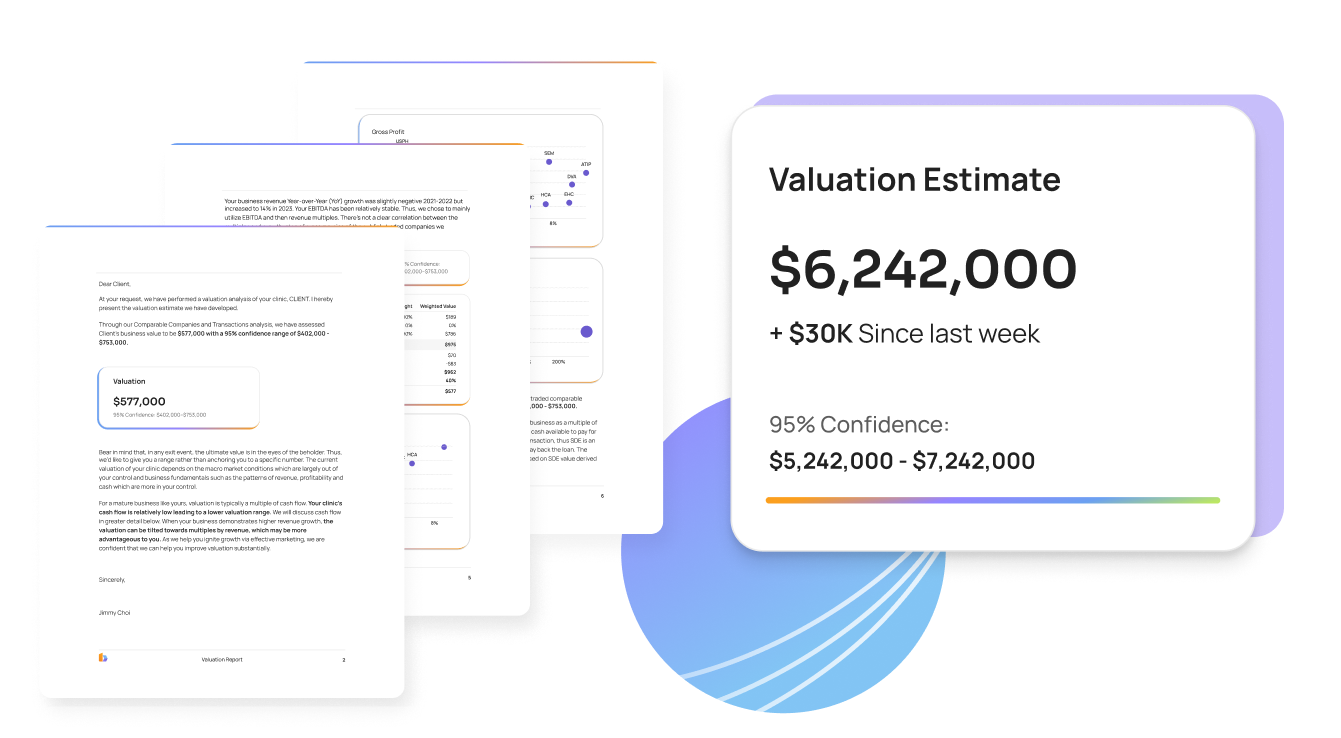
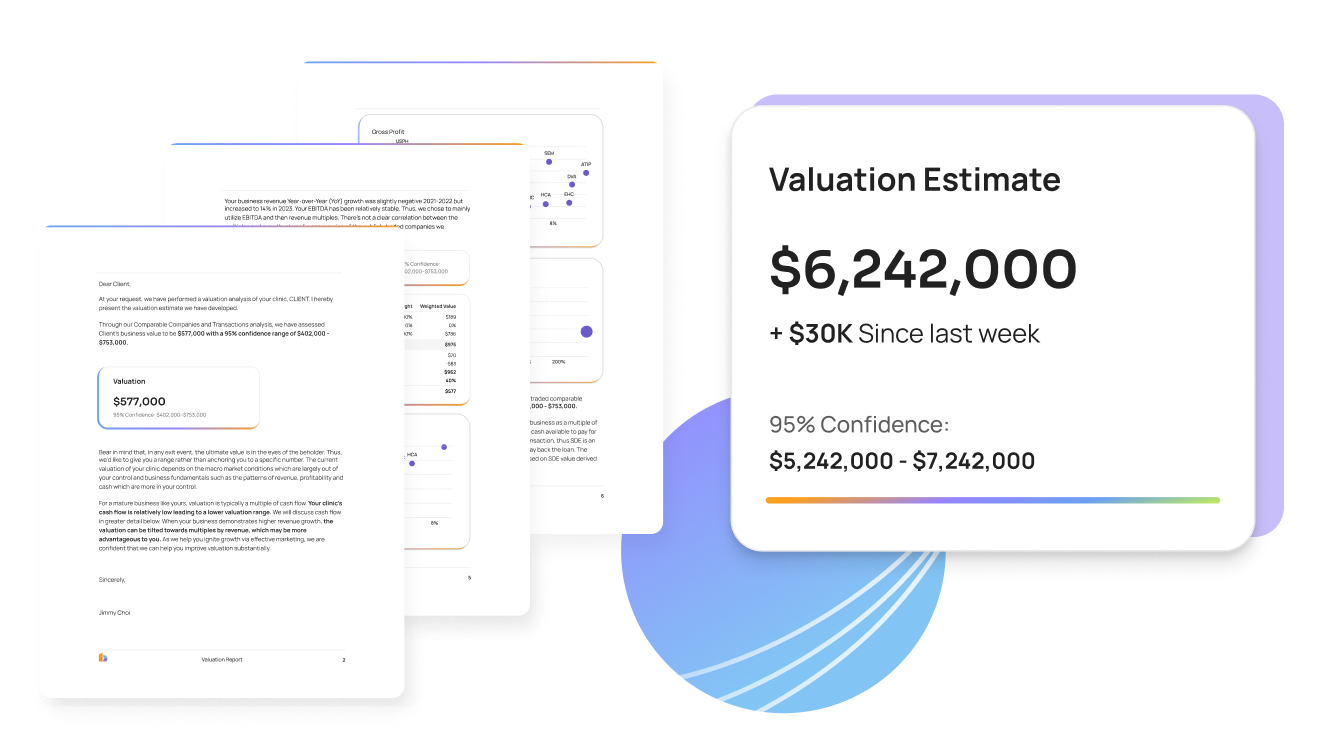
You receive a complete document you can hand straight to a lender or buyer, and your advisor walks you through every part of it: a clear value conclusion with the range and the methods used to reach it; normalized earnings that show what the business truly makes; market multiples and comparables tying your number to real, recent activity; and a read on risk and value drivers, so everyone understands what is behind the figure.
SBA lending in San Diego, and how it works with your valuation
Nationally the SBA guaranteed about 77,600 7(a) loans worth roughly $37 billion in fiscal year 2025, and a large share of those financed the purchase of an existing business rather than a startup. San Diego is a market where that matters more than most. About 111 completed sales were reported across the metro in 2025, at a median sale price near $277,500 on median revenue of roughly $470,000 and median cash flow around $135,500, and sellers closed at about 89 percent of their asking price.
Closing at 89 cents on the asking dollar is the part sellers here underestimate, and the wait compounds it: San Diego businesses took a median 159 days to sell, and roughly 398 were listed across the metro in the second quarter of 2026. That combination tells you what kind of buyer is actually closing here. Almost nobody buying a business at San Diego prices is writing a check for it. They are borrowing, usually through the 7(a) program, which means the loan rules, not the handshake, decide what they can pay you. For loans issued an SBA loan number on or after October 1, 2026, total transaction debt cannot exceed the valuation that supports the deal.
Every acquisition now requires an independent valuation from a qualified source, requested by and prepared for the lender, and the old exception for businesses valued at $250,000 or less is gone. The lender must also see the debt covered by historical earnings at a coverage ratio of 1.25x, measured on the last fiscal year end or an average of the last two. Knowing the sequence below is how you keep 159 days from becoming 300.
- Agree on a price. Buyer and seller reach a deal, often using a Bridge valuation as the starting point.
- Lender orders the independent valuation. For larger SBA deals, an unbiased third-party valuation is required before the loan can be approved.
- Underwriting reviews the report. Because Bridge reports arrive in the format underwriters expect, this step goes smoothly.
- Financing is approved and the deal closes. A clean valuation keeps everyone moving toward closing.
The levers that move your number
A valuation is not just a snapshot. It also shows you what is driving your value up and what is holding it back. Across most deals, the same handful of factors decide whether a buyer pays a premium or asks for a discount.
A business that runs without you
An SBA lender is underwriting the business the buyer will run, not the one you run today. The less the operation needs you in it, the less the loan looks like a wager on somebody who is walking out the door.
Cash flow that covers the loan payment
Around a 20% cash-flow margin is the floor most buyers and lenders look for. On an SBA deal the arithmetic is stricter: with median San Diego cash flow near $135,500, the earnings have to cover the buyer’s debt service and still pay them a living, or the loan does not clear.
Financials that survive underwriting
Three years of statements that reconcile to the tax returns. An underwriter who has to ask what a line item means is an underwriter adding weeks to a timeline that is already long here.
No single customer carrying the revenue
In a banking and corporate-services town, one large client can quietly become most of your revenue, and that is the risk lenders flag first. Losing a single account should not change whether the loan gets repaid.

Revenue a lender can forecast
Contracted or repeat revenue is worth more per dollar than project work, because a buyer and an underwriter can both model it forward.
Systems written down, team in place
Written processes and a team that makes decisions without you let a buyer picture day one, and let a lender believe the business keeps performing after you hand over the keys.
Owner Stories
THE PROCESS
Getting your valuation in San Diego
Our straightforward process gets you a defensible number without the guesswork.
Get your valuation report in just 3 days
1. Open your file
Tell Bridge about the business. It takes about 30 minutes.
2. Share your numbers
Upload three years of financial statements through a secure data room.
3. Get the certified report
Lender-ready and SBA-compliant, in 3 to 5 business days.
4. Walk through it
A walkthrough with your advisor is included, so you can explain the number to a lender in your own words.
Serving San Diego and Southern California
Bridge is headquartered in Lehi, Utah, and works with business owners across the United States, including San Diego, Chula Vista, Carlsbad, Escondido, Oceanside and the wider Southern California region. The San Diego business base skews toward the kinds of companies that finance well: professional and technical services, healthcare, construction and the trades, logistics, and business-to-business service firms across the county. It also carries a risk a lender appraiser looks for first. Defense and government work accounts for roughly a fifth of regional output and is spread across more than 2,000 contracting companies, so a strong San Diego business can still sit on heavy customer concentration in one agency or one prime contractor, with contracts that may not transfer to a buyer. That is the kind of issue an SBA valuation has to address head on rather than gloss over, and it is a common reason a financed price lands under the agreed one. Your dedicated advisor meets with you by phone and video, so you get the same hands-on guidance without leaving your office. To talk with someone about your business, schedule a free consultation.
Order a certified, SBA-compliant valuation, or start with a free estimate to see your range. Questions about your deal? Talk to a Bridge advisor.